
Overview
If your client has invested in a foreign mutual fund and sold their units during the financial year, you must report the resulting capital gain or loss in the appropriate section of the individual tax return.
For Australian tax residents, capital gains tax (CGT) may apply to the disposal of foreign investments, subject to the applicable Australian tax rules.
Important: Foreign mutual fund units should not automatically be reported under Item 20: Managed Funds simply because the investment is a mutual fund. The correct reporting method depends on the nature of the investment and the relevant tax reporting requirements.
Example Scenario
Your client holds units in a mutual fund located in a foreign country. During FY 2026, the client sold units acquired in different parcels, each with a different cost base and capital proceeds.
You need to determine where to record these transactions in LodgeiT.
Solution
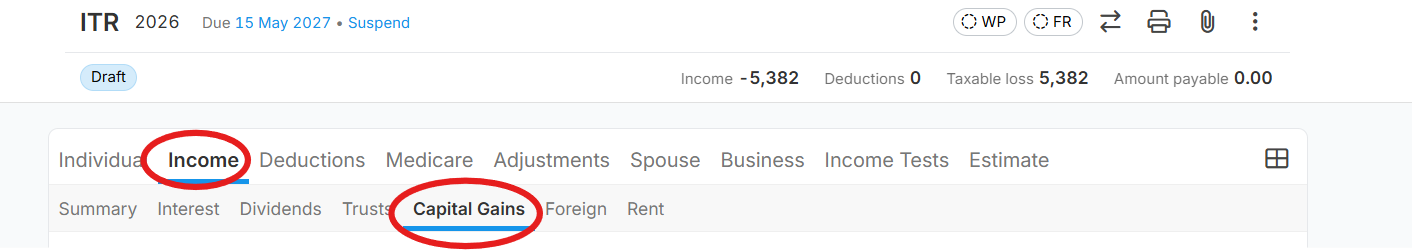
Step 1: Navigate to Item 18 – Capital Gains
Use the Item 18: Capital Gains section to record the disposal of the foreign investment where the transaction is subject to the CGT rules.
Step 2: Complete the Capital Gains Worksheet
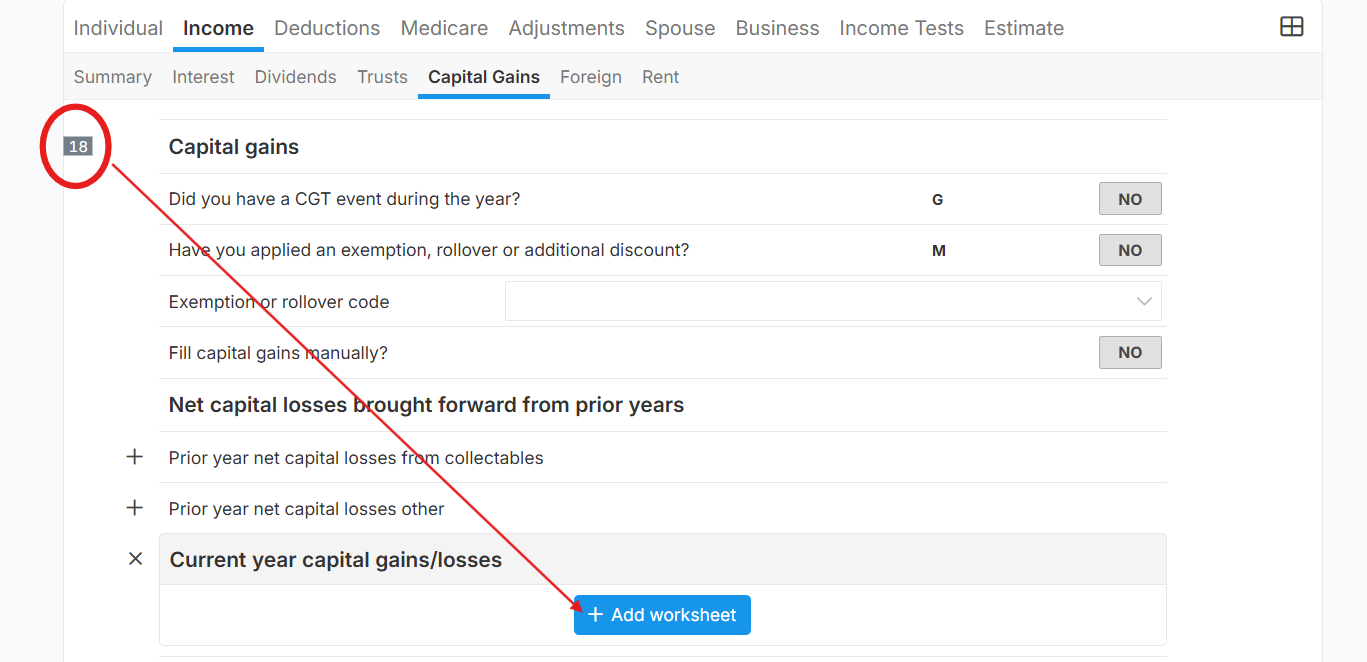
Enter the relevant details for each parcel of units, including:
Acquisition date
Disposal date
Capital proceeds
Cost base
Any applicable capital losses or CGT discount
Since the units were acquired in different parcels with different cost bases and proceeds, calculate the capital gain or loss for each parcel separately.
This helps ensure that the correct cost base, holding period, and applicable CGT treatment are applied to each disposal.
Step 3: Review the Capital Gain or Loss
Review the worksheet calculations and confirm that the resulting capital gains or losses are correctly reflected in the tax return.
Consider any applicable capital losses, CGT discounts, and foreign currency conversion requirements.
Step 4: Consider Item 20 – Foreign Income and Managed Funds
Do not use the Managed Fund worksheet at Item 20, label 18H, solely to report the capital gain from selling foreign mutual fund units.
Item 20 reporting depends on the type of foreign income received and the applicable reporting requirements. If the client received distributions from the foreign fund, those distributions may need to be reported separately from the capital gain arising from the sale.
If foreign tax was paid on the capital gain, assess whether the client is eligible to claim a Foreign Income Tax Offset (FITO) and report the foreign tax in the appropriate section of the return.
Summary
Item 18 – Capital Gains: Record the disposal of foreign investment units where the transaction is subject to CGT.
Multiple parcels: Calculate the gain or loss separately for each parcel, using the relevant cost base and proceeds.
Item 20 – Managed Funds: Use the relevant fields for reportable managed fund income or other applicable amounts, not as a substitute for reporting a CGT disposal.
Foreign tax paid: Assess FITO eligibility and report the foreign tax in the appropriate section.
Note: The correct treatment may differ depending on whether the investment is a direct holding of foreign fund units, an interest in a foreign trust, or an investment covered by specific attribution or foreign investment rules. Confirm the nature of the investment and the applicable ATO guidance before finalising the return.