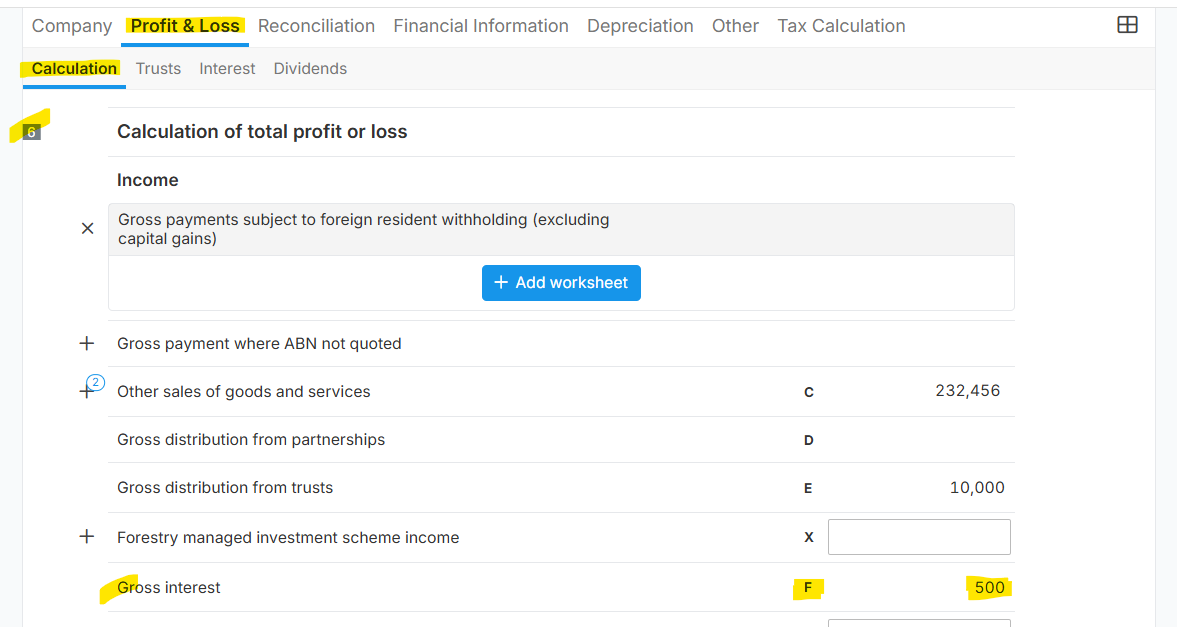
In the example below, taxable interest income is $500 while equivalent accounting income is only $500.
Therefore, there is no increasing or decreasing adjustment as per trust and partnership examples above.

Simply classify as Investment Revenue > Interest Received. Here is related guide on how to do the account mapping - Chart of Accounts and Mapping. There is no need to tag interest income in the accounts.

Notes:
- Manually enter the interest received amounts as tax fact at the "Gross Interest" section, so that there will be no "Increase/Decrease in interest" difference that will show in the Reconciliation tab.
- Ensure that there is an amount in "Gross interest on accounts" in the Interest tab, so that the Label 6F - "Gross Interest" will have a value. See below sample image for your reference: